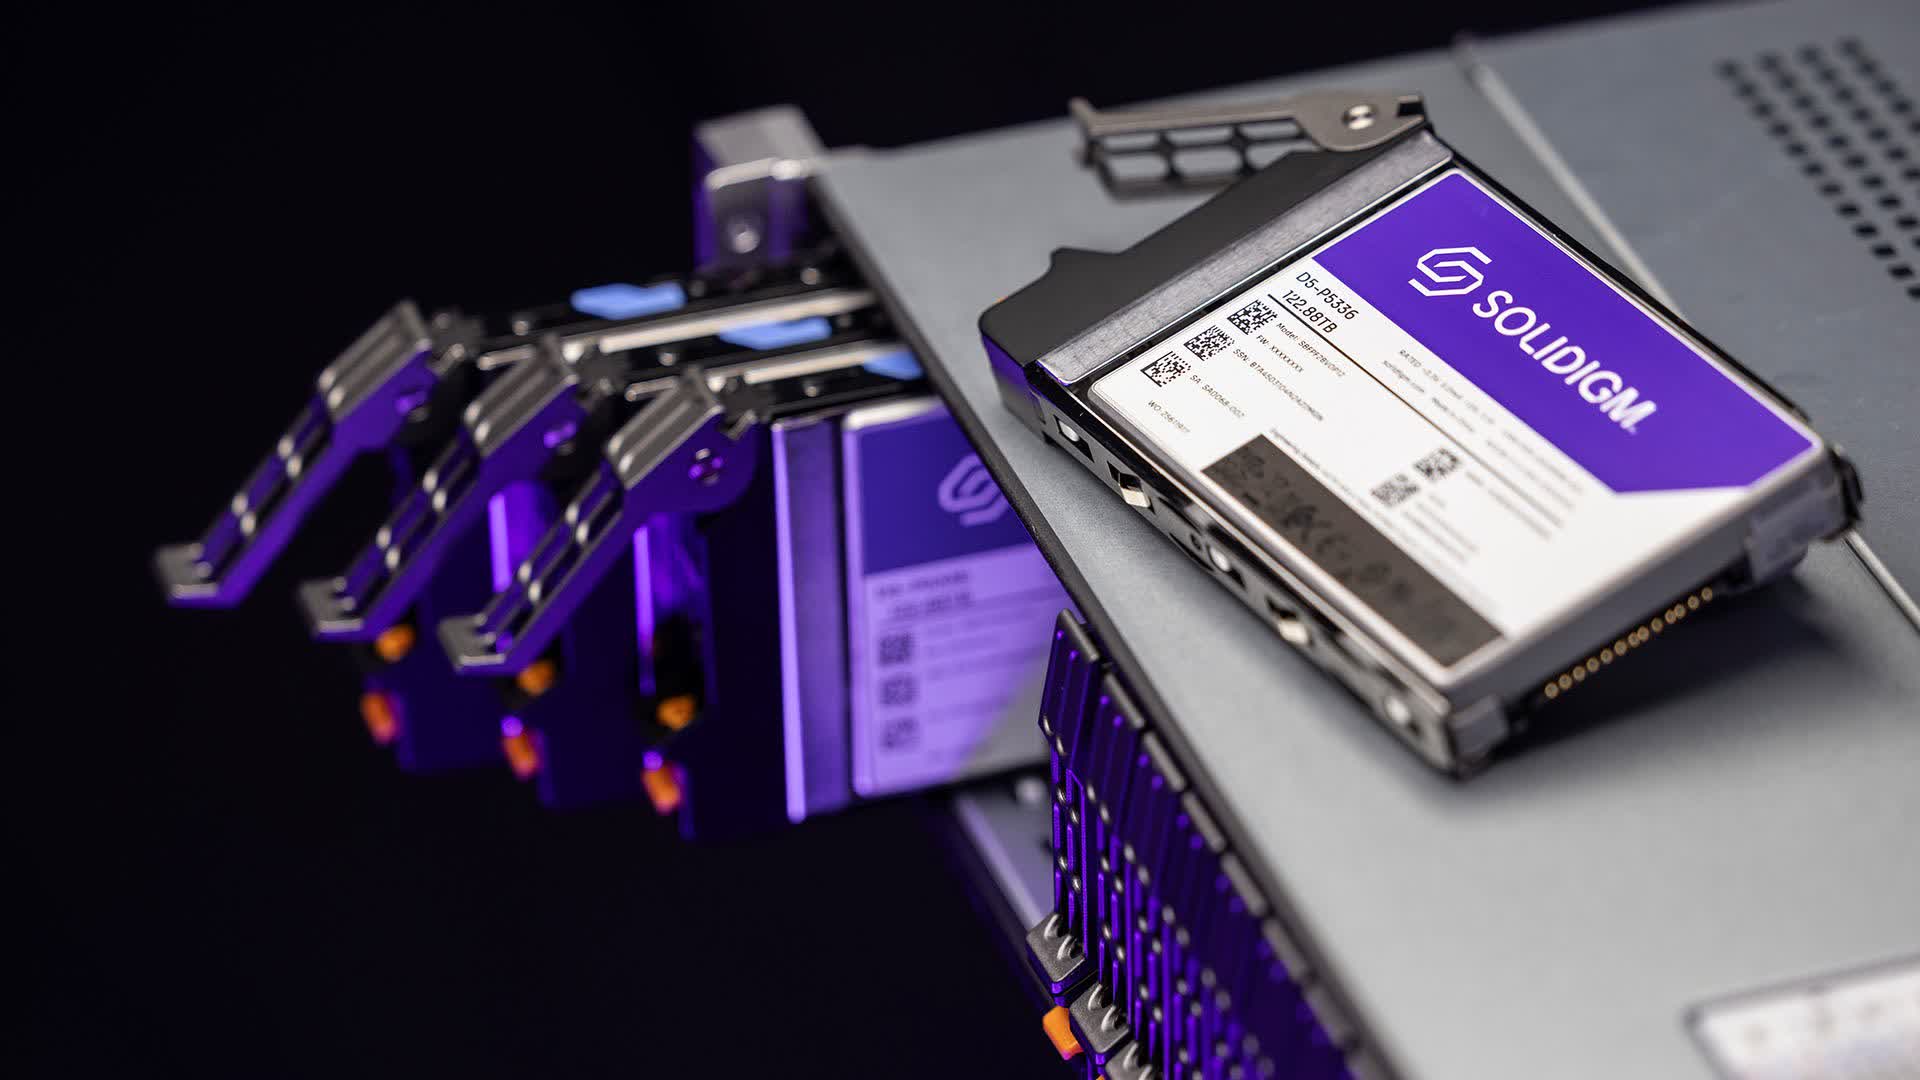
The takeaway: SK hynix says it still needs to build a US semiconductor fab for Solidigm as rising demand for AI storage strains the subsidiary's production capacity. But it has shelved a potential IPO that could have helped pay for the expansion. The decision shows how the need to expand chip production can clash with the financial conditions required to fund it.
A new facility would support Solidigm's high-capacity enterprise SSD business. Its existing manufacturing capacity barely covers projected requirements, making additional production a priority for parent company SK hynix.
Dropping the IPO leaves the expansion plans intact but the financing unresolved. SK hynix has stopped reviewing both an IPO and a pre-IPO funding round, citing market volatility and a correction in semiconductor stocks. The company says it will keep evaluating other funding options.
Solidigm plans to expand production of floating-gate 3D QLC NAND memory for its high-capacity data center SSDs. QLC stores four bits per memory cell, while the three-dimensional architecture stacks cells to boost storage density. Solidigm uses both technologies in drives built for enterprise storage.
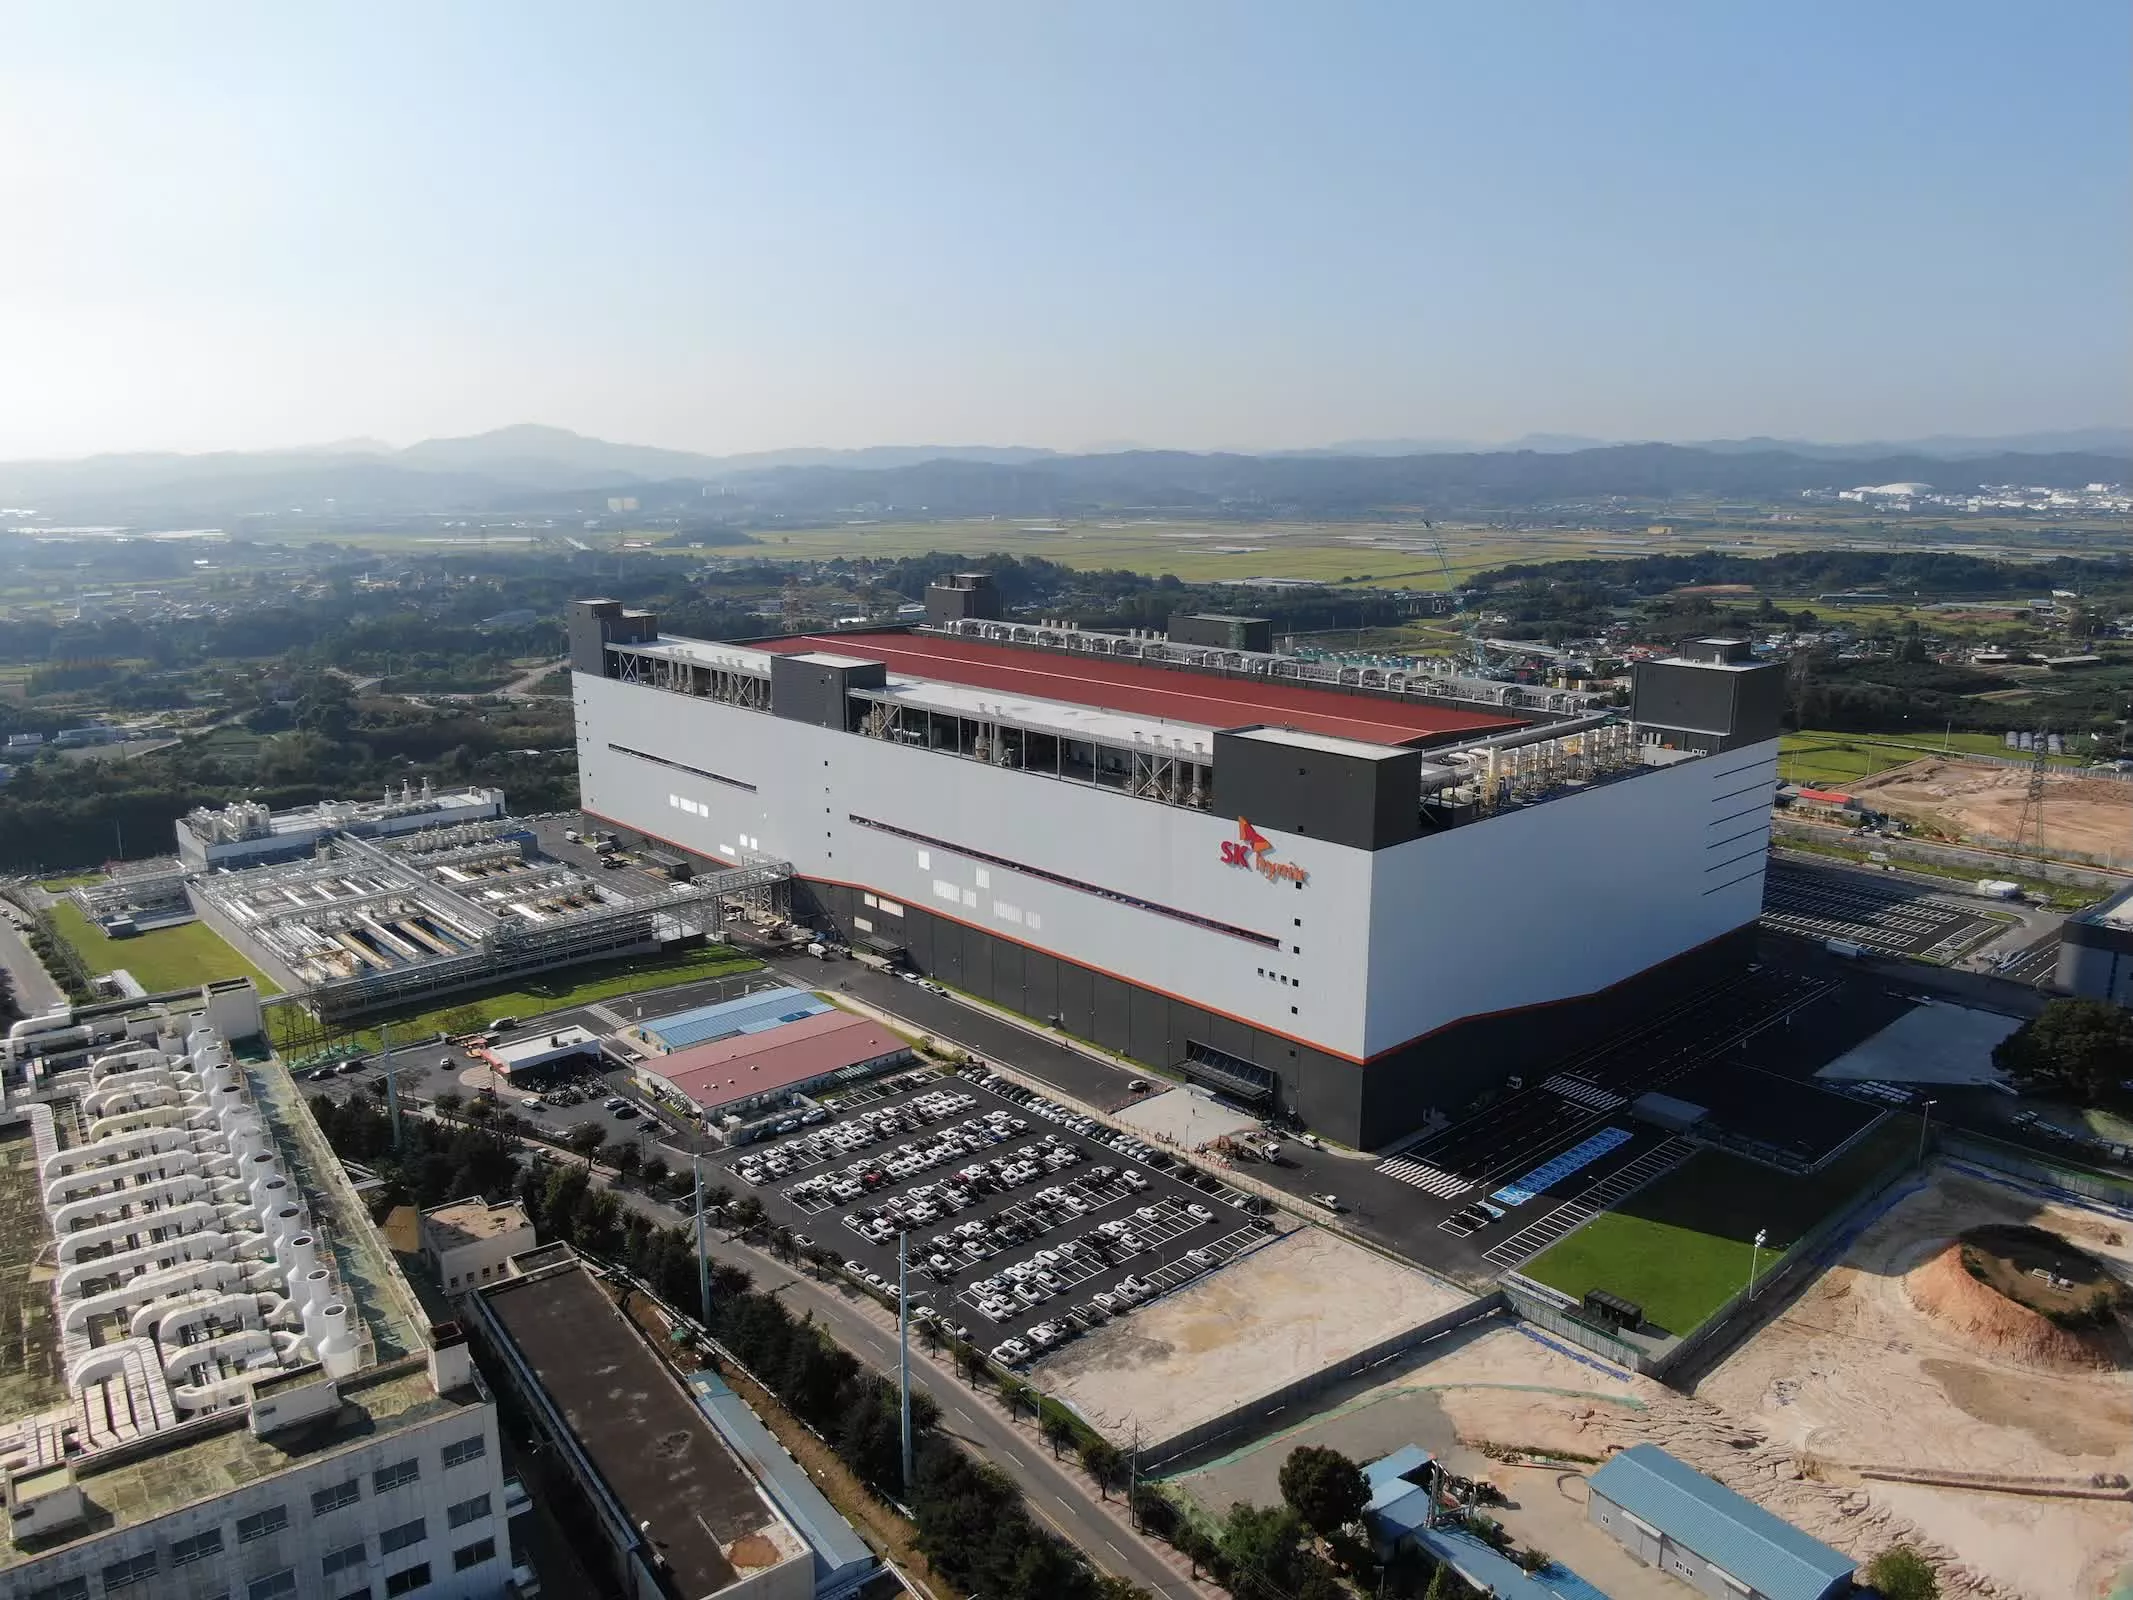
Growing AI infrastructure deployments are driving demand for high-capacity storage and straining production. To keep up, Solidigm needs to expand its manufacturing capacity, not simply broaden its product lineup.
A new US fab would increase output to support that growth and expand SK hynix's American manufacturing footprint. SK hynix has not said when the fab will open or how much it will produce. The project's scale also remains unclear. Building a modern 3D NAND fab can cost tens of billions of dollars.
SK hynix weighed direct investment, pre-IPO financing and a public offering to fund additional capacity. An IPO would have raised outside equity without adding debt and given Solidigm a market valuation separate from its parent's. SK hynix believes its share price doesn't fully reflect Solidigm's worth, but weak market conditions would leave the subsidiary undervalued.
SK hynix has not said how it will pay for the fab. It could use internally generated cash, borrowing, or a combination of both. Solidigm and SK hynix together hold 21.1% of the booming enterprise SSD market. Their combined share, however, doesn't reveal Solidigm's standalone profitability or how much cash it could contribute to the fab's construction.